Interest-only home loans are bucking the broader slowdown in mortgage lending.
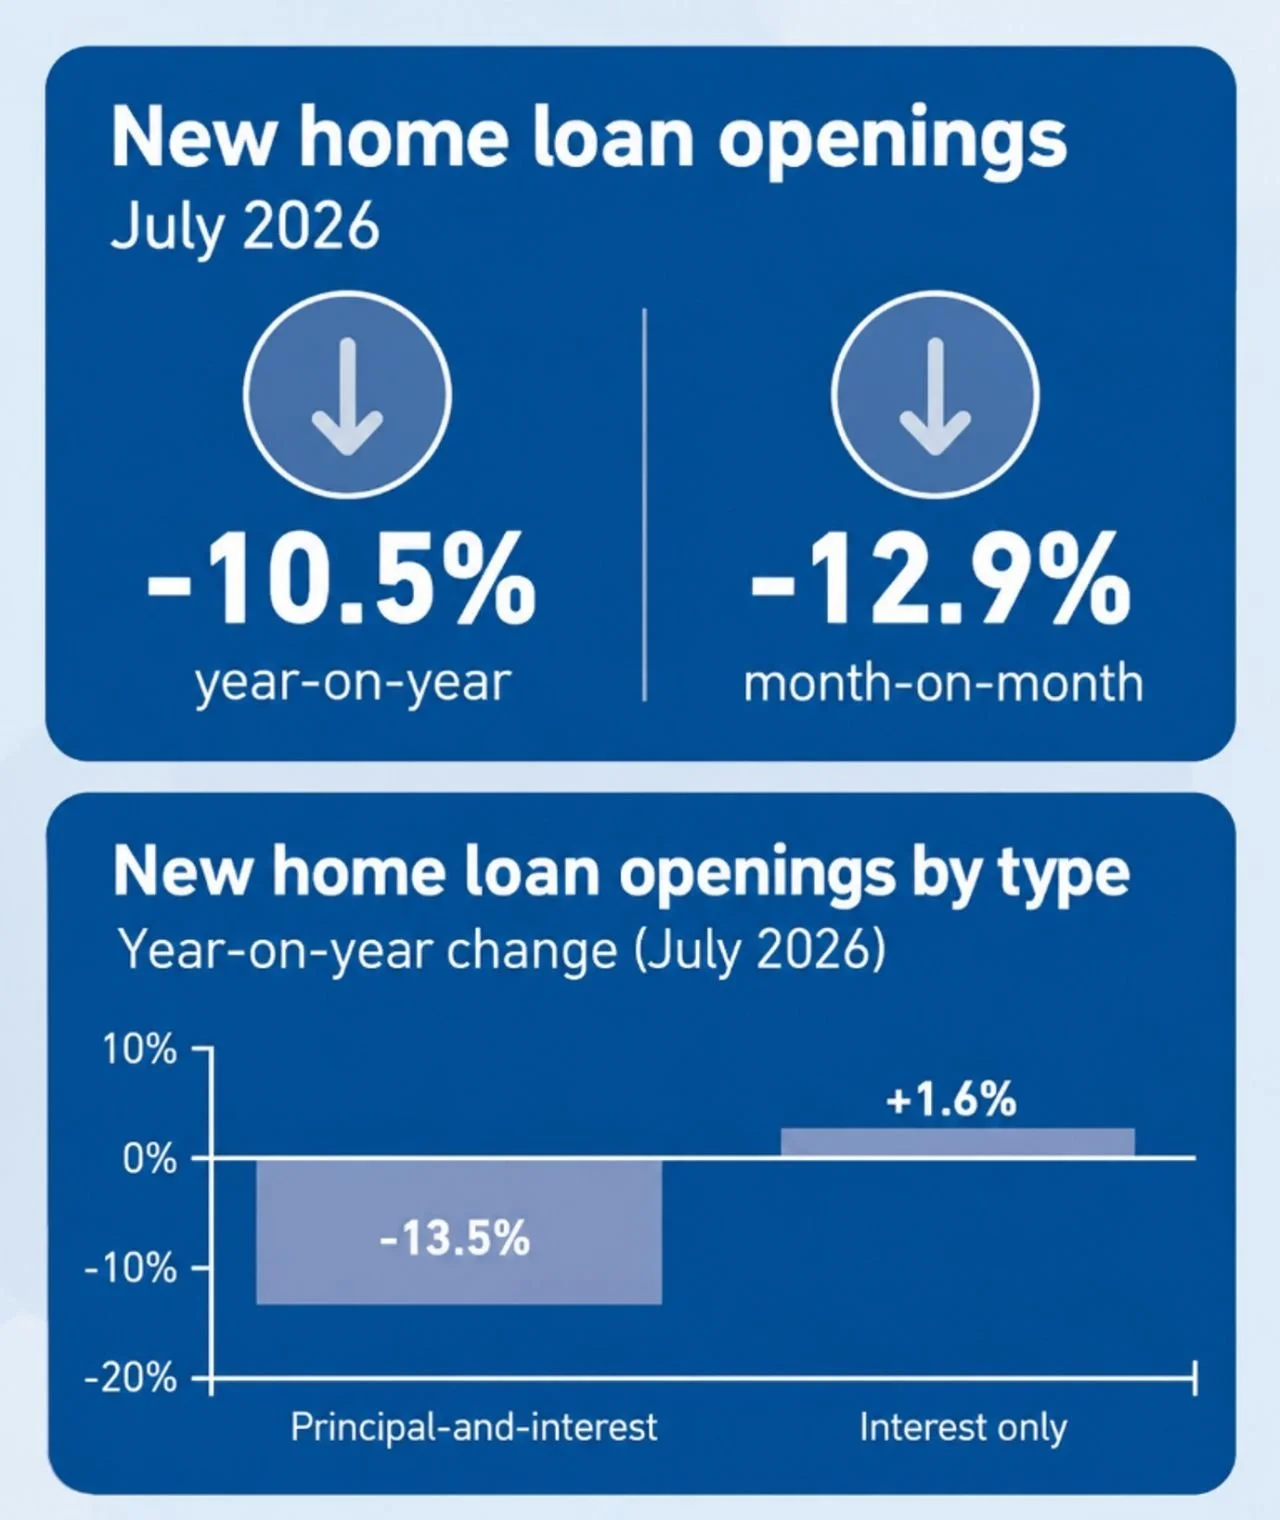
Experian's 2026 Housing Pressure Report reveals that new home loan openings fell 10.5% over the year to July 2026. But the figures reveal a striking difference between loan types: principal-and-interest openings declined 13.5%, while interest-only openings increased 1.6%.
Interest-only loans are commonly used by property investors to manage cash flow, making this lending option worth considering for those looking to expand their portfolios. By paying only the interest rather than reducing the principal, investors can keep their repayments lower during the interest-only period, freeing up funds to cover property expenses or build a financial buffer.
That flexibility can be valuable when managing multiple properties, particularly in a higher interest rate environment.
However, interest-only loans aren't suitable for everyone. The principal remains unchanged during the interest-only period, and repayments generally increase when the loan switches to principal and interest.
Choosing the right repayment structure can make a significant difference to an investor's cash flow, both now and in the years ahead.
Comparing investment loans across lenders can help investors find a structure that supports their cash flow and longer-term portfolio plans.
About the author – Alex Veljancevski is a Sydney Mortgage Broker with Eventus Financial, which assists first home buyers, investors, upgraders and borrowers seeking to refinance to a better deal on their home loan.